
Deferit: Split Bills, Pay in 4
- Rating
- 4.5
- Downloads
- 1.00M
- Content Rating
- Everyone
Deferit: Split Bills, Pay in 4 - Screenshots
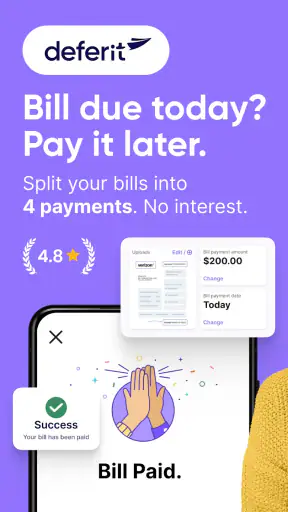
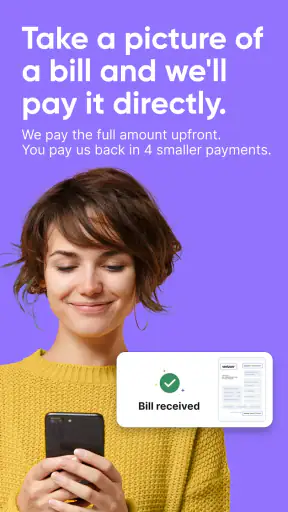
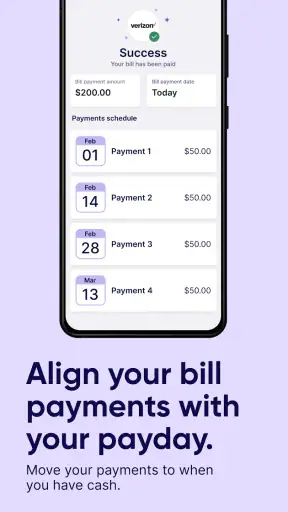
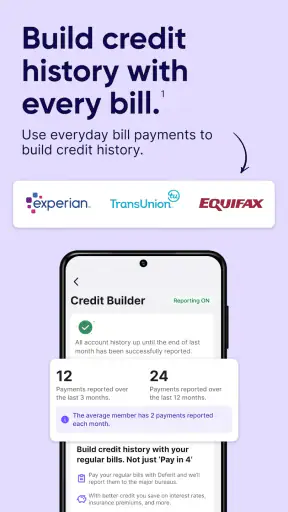
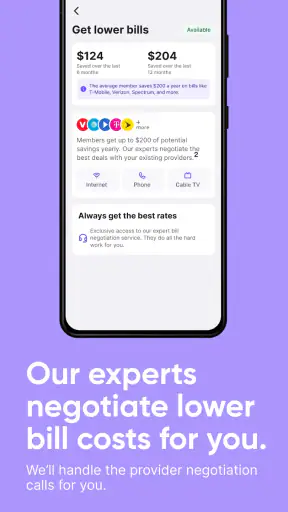
Pros
- Helps spread eligible bills across multiple scheduled payments.
- Payment reminders can make recurring expenses easier to track.
- Useful for users managing tight cash flow between paychecks.
- A clear payment schedule can reduce the stress of large due dates.
- May help avoid late fees when payments are made on time.
Cons
- Approval and available payment amounts may vary by user.
- Missed installments can lead to fees or account restrictions.
- Not every bill or service provider may be supported.
- Splitting payments can make budgeting harder if used too often.
- Requires reliable income and payment access for scheduled installments.
Deferit: Split Bills, Pay in 4 - Description
- App Name
- Deferit: Split Bills, Pay in 4
- Package Name
- au.com.deferit.app
- Developer
- Deferit
- Category
- Finance
- Last Updated
- Oct 28, 2021
- Version
- 3.0.6
When a bill arrives before payday, the problem is often timing rather than unwillingness to pay. Deferit: Split Bills, Pay in 4 is built for that awkward gap. It is a finance app from Deferit that lets eligible users divide bills into four smaller payments without interest, turning one large due amount into a series of more manageable ones. After spending time with it, I found the appeal easy to understand: it is less about clever budgeting and more about smoothing out an uneven month.
That distinction matters. This is not a full banking replacement, a complete budgeting dashboard, or a way to make expensive bills disappear. It is a focused tool for handling bills when the calendar is working against you. The first experience feels reassuring because the idea is simple, but the lasting value depends on whether you can use the arrangement deliberately rather than treating it as extra spending room.
From immediate relief to a lasting financial habit
Why the first week feels useful
The strongest part of the app is its directness. Instead of asking me to reorganize every account or build a detailed financial plan, it centers on the bill that needs attention now. The four-payment structure is easy to explain to yourself: deal with a smaller initial amount, then keep track of the remaining installments. For someone facing several due dates close together, that can feel more practical than waiting for a perfect monthly budget.
The no-interest promise is also central to the experience. It gives the service a different feel from carrying a balance on a credit card, where the cost can grow if repayment slips. Still, “no interest” should not be interpreted as “no responsibility.” The scheduled payments remain real commitments, and the app works best when I already know where those future amounts will come from.
I can imagine the first useful scenario clearly. Suppose a household has a utility bill due during a week when rent, transport costs, and groceries have already taken most of the available money. Splitting that bill into four payments may protect the rest of the week’s cash flow. The benefit is not that the bill becomes cheaper; it is that the pressure is spread across time. That can be valuable when the alternative is missing a due date or relying on a more expensive form of borrowing.
The app is free to download, and its Everyone content rating makes it approachable for a broad audience. It has reached over one million installs and holds a 4.5 average from around twenty thousand ratings, which suggests that the basic idea resonates with many people. Those figures do not replace personal judgment, but they do make the service feel established rather than experimental.
What I would check before relying on it
My first recommendation is to treat the setup as a decision point, not a quick rescue button. Before splitting a bill, I would write down the four expected payment dates and compare them with rent, subscriptions, food, travel, and any other fixed commitments. The smaller first payment can make the present look comfortable while quietly making the next few weeks tighter.
A useful habit is to keep a small calendar note for every active arrangement. I would record the bill name, the original amount, the payment schedule, and the account that needs to be ready. This is especially important if several bills are being handled at once. A service designed to simplify one large payment can become harder to follow when multiple smaller obligations overlap.
I would also use it for predictable needs rather than impulse purchases. A recurring household bill, an essential service, or another unavoidable expense is easier to justify than using payment splitting to stretch a discretionary purchase. That boundary is one of the most important differences between a cash-flow tool and a habit that postpones difficult decisions.
How it compares with familiar alternatives
The usual alternatives each solve a different part of the problem. A traditional savings buffer is healthier when it is available because it avoids creating future payment obligations. A bank account with automatic budgeting tools may be better for understanding where money goes over an entire month. A credit card can offer convenience, but its costs and repayment structure may be less predictable if a balance is carried.
Deferit sits between those options. It is more focused than a budgeting app and potentially less costly than interest-bearing credit, but it does not build savings or explain the rest of a household’s finances. I see it as a bridge for timing problems, not a replacement for an emergency fund. If I had enough cash set aside, I would normally pay the bill directly and keep the process simpler.
That comparison also clarifies who should skip it. Someone who regularly has no money available for the later installments may need debt advice, a spending review, or a conversation with the bill provider instead. Splitting payments cannot fix an income shortfall that repeats every month. It can only make a particular payment schedule easier to absorb.
Where the month-to-month value comes from
The app earns a place on a phone when it solves the same kind of problem repeatedly without demanding constant attention. For me, its recurring value would come from planning around uneven billing cycles. Some months contain several annual or irregular expenses, while others are calmer. A payment-splitting option can make those peaks less disruptive when used selectively.
The key word is selectively. If every bill is divided automatically in my mental routine, the original advantage starts to fade. Four smaller payments are still four payments, and they can overlap with other arrangements. The service is most useful when I choose it because a specific bill lands at an inconvenient time, not because I have stopped checking whether the total fits my budget.
That makes the app particularly relevant to people paid on a regular schedule but facing bills that arrive on different dates. It may also suit households that can cover their obligations overall but experience short periods of low cash. In those cases, the app can reduce the need to make several last-minute transfers or move money between accounts.
I would not describe it as a long-term financial plan. It does not, by itself, encourage saving for the next bill, reduce the bill’s underlying cost, or reveal whether a service has become too expensive. Its lasting contribution is narrower: it can add flexibility to the payment calendar. That is useful, but only if I continue to manage the calendar outside the app as well.
Small workflows that make the service more manageable
One practical workflow is to use the app only after sorting bills into three groups: essential and fixed, essential but variable, and optional. The first group is where payment splitting may have the clearest purpose. The second needs extra caution because the amount may change, while the third usually deserves a spending decision before any payment arrangement.
Another helpful approach is to review the next installment before accepting a new split. I would ask whether that payment will collide with another scheduled obligation. This simple pause catches a common trap: each individual arrangement looks affordable, but their combined dates create a difficult week.
I would also keep an end point in mind. Once cash flow improves, paying bills directly again may be preferable. The app should support a temporary adjustment, not become invisible infrastructure that I depend on indefinitely. That mindset preserves its usefulness because I remain aware of the original due amounts and the total commitments.
For a household, communication matters too. If one person uses the service while another handles the shared budget, both need to know which bills have been divided and when the later payments are expected. Otherwise, the same bill may be counted twice or the future installment may be mistaken for spare money. The app can organize the payment arrangement, but it cannot replace a shared household record.
The maintenance burden after the novelty fades
The biggest maintenance task is not technical; it is financial awareness. Every split creates a small item to remember. One arrangement may be easy, but several can turn a clean monthly budget into a collection of staggered obligations. I would therefore check the app whenever I review my bank balance, rather than waiting for a payment to surprise me.
Version 3.0.6 is the current version, and the app supports devices running Android 7.0 or later. That gives it a reasonably broad Android reach, although device compatibility is still something I would check before planning around it. A finance app also deserves the same care as a banking tool: I would keep the device updated, use a secure screen lock, and avoid handling account details on an untrusted network.
There is another kind of maintenance that is easy to overlook: deciding whether the service is still solving the original problem. If my income and bill dates become more stable, direct payment may be less complicated. If I need a broader view of spending, a dedicated budget app may offer more insight. Keeping an app installed is not automatically worthwhile simply because it helped once.
The developer, Deferit, has made the product’s purpose narrow enough to understand quickly. That is a strength because I do not have to learn a large financial system before using the central function. It is also a limitation because people expecting detailed planning tools may find themselves maintaining a second system for budgets, savings, and longer-term goals.
Where users may feel fatigue
The first source of fatigue is repetition. A payment plan can feel tidy at the start, but checking several upcoming installments requires discipline. The more often I use the feature, the more important it becomes to track the total amount still committed, not just the next payment.
The second is psychological. Smaller payments can make a bill feel less serious than it is. That can encourage me to accept another purchase or arrangement before the first one is finished. The app’s convenience is therefore also its main risk: it reduces immediate friction, and reduced friction can be helpful or harmful depending on the decision behind it.
The third is the possibility of using the service for a problem that needs a different solution. If a bill is unaffordable even when divided into four parts, the right next step may be contacting the provider, reviewing usage, cutting another expense, or seeking qualified financial guidance. Continuing to split payments in that situation only postpones the pressure.
I would also be cautious when my income is irregular. A fixed installment schedule may be comfortable during a strong week and difficult during a weak one. The app is easier to justify when future income is reasonably predictable. For freelancers, seasonal workers, or anyone dealing with frequent income gaps, a cash reserve may offer safer flexibility than adding more scheduled payments.
Who gets the most from it
I think the best fit is someone with a temporary cash-flow mismatch, a clear view of upcoming income, and enough room to cover all four payments. That person may not need a complex financial platform; they need a controlled way to move part of a bill across the month.
It can also help people who dislike using revolving credit for ordinary bills. The fixed split is easier to reason about than an open-ended balance, provided the repayment dates are respected. For a household managing several due dates, the app may offer breathing room during particularly crowded periods.
The weaker fit is someone already juggling missed payments, relying on one bill to cover another, or unable to predict the next month’s income. In that situation, the app may feel helpful during the first few days but add pressure later. I would also choose a conventional budgeting tool instead if my main goal were tracking categories, building savings targets, or understanding long-term spending patterns.
My long-term verdict
After the initial novelty wears off, the app’s value depends on restraint. The four-payment approach is genuinely practical for a narrow situation: an essential bill is due now, the full amount is awkward today, and the later payments are already affordable. In that setting, it can make a stressful week more manageable without the interest associated with some familiar credit options.
It does not earn permanent space on my phone merely because it can divide bills. It earns that space when I use it occasionally, record the future commitments, and remove the pressure once my cash flow is normal again. The maintenance is light for one carefully chosen bill, but it becomes meaningful when arrangements accumulate.
With a 4.5 average across around twenty thousand ratings, the reception is encouraging, and the free entry point makes trying the service straightforward. Still, I would judge it by my own repayment pattern rather than popularity. A high rating cannot tell me whether the next four payments fit my particular month.
My honest recommendation is to see Deferit as a short-term cash-flow tool, not free money and not a substitute for savings. I would use it for a necessary bill during a temporary squeeze, keep a written record of every installment, and compare the total schedule with my normal budget before accepting another split. Used that way, it has a clear and lasting purpose. Used automatically for every expense, it can create exactly the kind of financial clutter it was meant to reduce.
FAQ
What is Deferit: Split Bills, Pay in 4?
Deferit is a bill-management and payment app designed to help users cover eligible bills and spread the cost over smaller scheduled payments. Instead of paying the entire amount at once, you can submit supported bills through the app and follow a repayment plan. Availability, supported billers, limits, and payment options may vary depending on your country, account status, and the current terms offered by Deferit.
How does Deferit’s Pay in 4 feature work?
The Pay in 4 option divides an eligible bill into four scheduled installments, making a large payment easier to manage within your budget. You normally provide the bill details, review the proposed repayment schedule, and authorize the required payments before confirming. It is important to check the exact due dates, fees, eligibility requirements, and consequences of a missed installment because these details can differ by user and region.
What bills can I pay or split with Deferit?
Deferit is intended for common household and personal bills, but the exact categories accepted by the app can change. Depending on your location, you may be able to submit expenses such as utilities, telecommunications, insurance, rent-related payments, or other recurring services. Before downloading or relying on the service, review the in-app biller list and eligibility rules, since not every provider, invoice type, amount, or overdue bill will necessarily be supported.
Does Deferit charge fees or interest?
The cost of using Deferit depends on the service, repayment option, country, and account terms shown during checkout. Some plans may include membership costs, transaction fees, late fees, or other charges, while the advertised installment amount may not represent the total cost in every situation. Always read the payment summary and terms before confirming a bill, and compare the total repayment amount with the original bill.
Is Deferit safe, and what happens if I miss a payment?
Deferit may require personal, billing, and payment information to process your requests, so users should review its privacy policy, security information, and permissions before creating an account. Missing an installment can lead to failed-payment charges, account restrictions, collection activity, or other consequences depending on the applicable agreement. Keep your linked payment method funded, monitor reminders, and contact Deferit support promptly if you expect difficulty making a scheduled payment.


